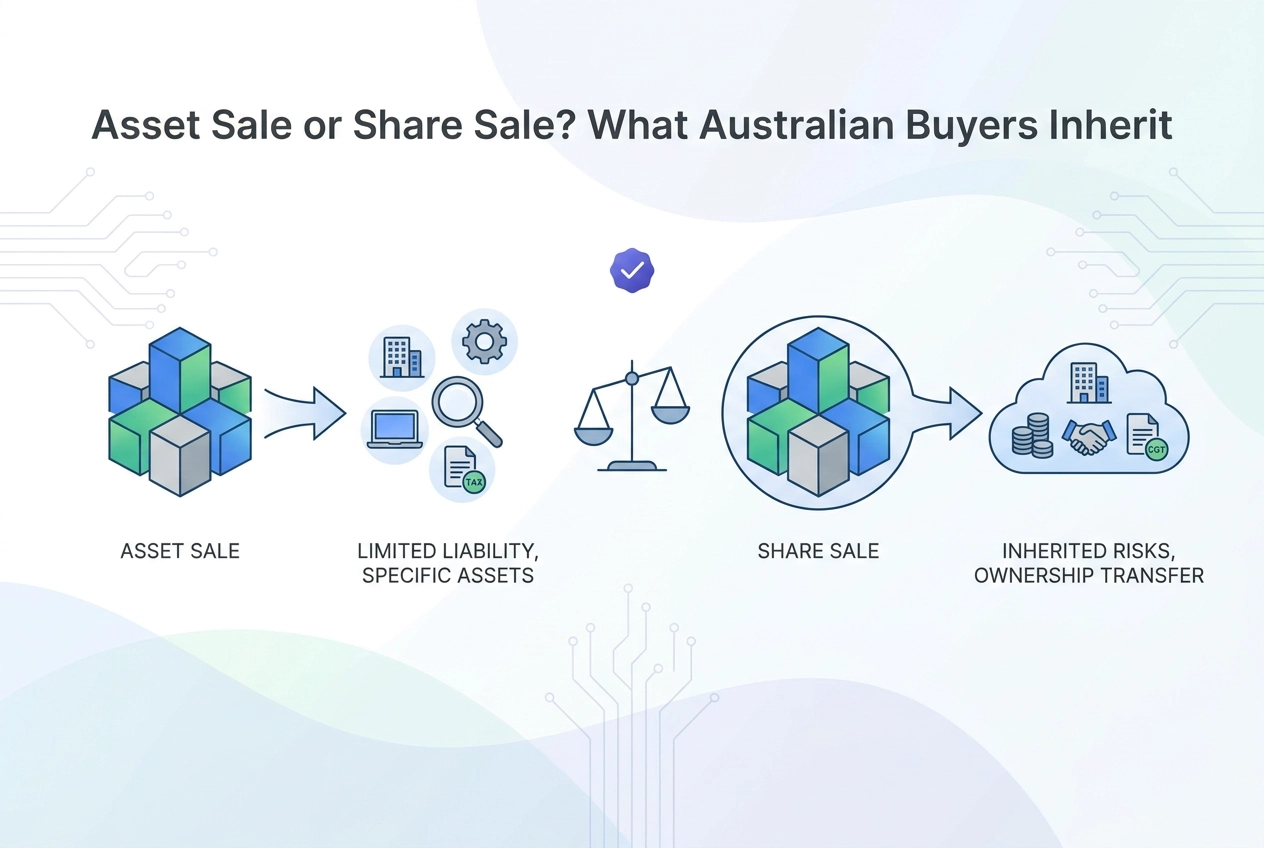
The structure of the deal decides what you inherit. When you buy a business in Australia, an asset sale and a share sale are two different transactions with two different risk profiles, and the choice should follow your diligence findings, not whichever structure the seller's accountant proposed first.
Buy the assets and you select what transfers. The corporate shell, its tax history and its undisclosed liabilities stay with the seller. Buy the shares and you acquire the company itself, along with everything attached to it: contracts, employees, liabilities and history, known or unknown. That difference shapes everything that follows.
This post works through what each structure actually transfers, how warranties, indemnities and disclosure letters allocate risk, what happens to employees under the Fair Work transfer-of-business rules, and how contracts and leases move through consent, assignment or novation. It covers transfer duty and landholder duty thresholds by state, GST going concern treatment against input-taxed share sales, and why the seller's CGT position shapes the offer you receive. It closes with a decision framework, a diligence checklist and your next three moves.
Why the structure of the deal decides what you inherit
Settlement is not the finish line. An employee underpayment claim, an ATO assessment, a broken supply contract or a lease default will land on one party after the deal closes, and the structure you choose decides which party that is.
In a share sale you buy the company itself. You get its assets, contracts, staff and trading history, and its liabilities, known and unknown. In an asset sale you buy selected assets. The corporate shell, its tax history and its undisclosed exposures stay with the seller.
The trade-off sits underneath that. A share sale keeps everything running the day after settlement because nothing needs to be reassigned: leases, licences, supply agreements and employment records all continue in the same entity. An asset sale gives you a cleaner starting position at the cost of rebuilding those arrangements, usually with third-party consent.
Do not accept the seller's preferred structure as the default. The seller's accountant is optimising the seller's CGT position, not your risk exposure, so treat their preference as information rather than instruction. The structure should follow what due diligence on the business turns up.
Scope of this piece: duty treatment covered here is Queensland and Victoria, statutory references are cited, and the tax illustrations are labelled as illustrations rather than market data.
What an asset sale actually transfers
An asset sale is a pick-and-mix transaction. You name the plant and equipment, stock, goodwill, business name, intellectual property and customer lists you want, and the contract can also list which liabilities transfer. Anything not on that list stays with the seller.
The company itself stays behind. Its tax history, lodged returns, undisclosed creditor claims and contingent liabilities tied to the entity remain the seller's problem. That separation is why cautious first-time buyers default to an asset structure.
Contracts do not travel automatically. Every supplier, customer, franchise or licence agreement must be assigned or novated, and most require the counterparty's consent. A refusal, or a demand to renegotiate terms, is a live settlement risk, not a hypothetical one.
Employees transfer under the Fair Work Act's transfer-of-business rules, sections 311 to 314. A non-associated buyer can choose not to recognise prior service, which affects annual leave accrual, redundancy entitlements and unfair dismissal eligibility. The Fair Work Ombudsman explains how these rules operate when a business changes owners.
Duty and GST sit on this structure too. Queensland asset sales generally attract transfer duty on the business assets, and GST applies unless the sale qualifies as a going concern. Get that wrong on a $600,000 deal and you are looking at roughly 10% of the price in unexpected tax. Model that treatment early, alongside the legal completion and post-sale obligations that follow settlement.
What a share sale actually transfers
Where an asset sale lets you pick what you buy, a share sale gives you no choice. The entity itself changes hands, so everything inside it moves with it. On settlement the company owns the same assets, owes the same debts, employs the same staff on the same terms and holds the same contracts and licences it held the day before. Nothing needs renegotiating for trading to continue.
The tax history follows the entity rather than the seller. Prior returns, franking balances, carried-forward losses, an ATO review in progress and any unpaid superannuation or PAYG are yours to deal with, because the taxpayer has not changed. Carried-forward losses survive only where the company passes the continuity of ownership test or the same business test, so confirm that before you count them. Sellers usually propose the structure that protects their own tax outcome, so understand how a business sale works from the seller's side before you accept it.
Continuity is the upside. Leases, supply agreements, accreditation, licences and qualified staff carry over without third-party consent, which matters most in regulated or heavily contracted businesses.
Contingent liabilities hold the real exposure. A warranty claim on work done three years ago, a Fair Work complaint about last year's termination, an open insurance claim or an unrecorded employee entitlement shortfall will not appear in a revenue and profit view of the business.
Risk is reallocated by contract, not removed. Warranties, disclosure letters, indemnities and liability caps decide who pays when a stated fact proves wrong, and on larger transactions warranty and indemnity insurance shifts that exposure to an insurer.
Liabilities and risk allocation: warranties, indemnities and disclosure
Warranties are statements of fact: revenue is what the accounts say, there are no undisclosed tax liabilities, the plant is owned outright. If a statement is wrong and the warranty is unqualified, you have a claim. Qualification is the catch. The seller's disclosure letter lists exceptions, and anything disclosed is carved out of the promise, so a warranty can survive negotiation and still protect you from very little.
Indemnities are the stronger tool. They cover a specific risk you already know about, such as an ATO review of a prior year or a pending employment claim, and they pay dollar for dollar rather than leaving you to prove general damages. Ask for one wherever diligence identifies a known exposure.
Caps, baskets and time limits decide whether a claim is worth running. A low cap and a 12-month window can leave a real loss with no practical remedy, which is why these terms sometimes matter more than the headline price. In UK and US deal surveys, half of respondents reported basket thresholds of 3% of purchase price or less.
On a share sale, exposures the seller never knew about sit outside the warranty package entirely. An asset sale avoids that class of risk by leaving the entity behind.
The warranty package is not a substitute for diligence. If you have not read every disclosed item against the accounts, you cannot tell whether a warranty still protects you or has been qualified into nothing. Those are the risks buyers most often underestimate when buying an existing business, and they sit in exactly this gap.
Employees: who keeps their job, service and entitlements
The warranty package decides who pays when a stated fact proves wrong. Employment runs on a different rule: the structure decides who the employer is.
In a share sale the employer does not change. The same entity employs the same staff, so service, leave balances, redundancy calculations and unfair dismissal eligibility carry over untouched. That continuity is a genuine advantage and a genuine exposure, because any existing entitlement shortfall is now yours to fund.
An asset sale runs through transfer-of-business rules in sections 311 to 314 of the Fair Work Act 2009. Where the buyer is not associated with the seller, prior service can be disregarded for annual leave, redundancy pay and unfair dismissal eligibility.
That choice is not free. Disregarding service can trigger a transfer obligation to pay out accrued entitlements, sour the workforce at the worst possible moment, and cost more in recruitment and retraining than carrying the records would have.
Ask for payroll data before committing to a structure: leave balances, superannuation history, award classifications, individual flexibility arrangements, contractor versus employee status and any current disputes. Entitlement exposure is one of the top reasons buyers walk away after diligence, so it belongs in the first round of questions, not the last. Australian Businesses for Sale: What Buyers and Sellers Need to Know sets out the wider market picture for anyone weighing how to buy a business in Australia.
Treat a share sale with an underpaid wages exposure as a price-adjustment conversation rather than a walk-away. The number is usually quantifiable and a specific indemnity can shift it back to the seller.
Contracts and leases: consent, assignment and novation
Employment contracts are one category. Every other agreement transfers by its own rules, and two words do most of the work.
A novation replaces a party to the contract outright and needs everyone's agreement: the seller, the buyer and the counterparty. An assignment transfers the benefit only, and the seller can stay on the hook for performance unless the counterparty releases them. Well-drafted agreements require consent for either.
In a share sale nothing needs to move because the entity stays the same, but change-of-control clauses still bite. A landlord or key customer can hold a termination right triggered by the share transfer, so reading those clauses is a diligence priority rather than an afterthought. That is a core step in due diligence when buying a business, not a formality.
In an asset sale, the lease must be assigned or replaced. If the landlord wants new terms, a personal guarantee or a rent increase as the price of consent, that cost belongs in your deal model before you sign.
Queensland tightened the timing. From 1 August 2025, a landlord whose consent is required must decide within one month of receiving full particulars and give reasons for refusing. The clock starts only when complete information reaches them, so how you lodge the request matters.
Map agreements by consequence rather than value: franchise agreements, supplier exclusivity, software and licence terms, council and state approvals and key customer contracts each carry their own transfer mechanics and their own failure modes.
Consent is not the only structure-sensitive cost. Duty follows the same logic.
Transfer duty and landholder duty: what changes from state to state
Consent is one cost of restructuring a deal. Duty is often the bigger one, and it follows the state where the land and assets sit, not the state where you sign.
Queensland asset sales. An asset sale generally attracts transfer duty on the business assets you acquire, and that reaches beyond plant and equipment. Goodwill and certain other dutiable property form part of the dutiable value, broadly the higher of market value and the agreed price. Model this at the deal-modelling stage, not at settlement.
Queensland share sales. A share sale avoids asset-level transfer duty but can trigger landholder duty instead. Where the company holds Queensland land worth $2 million or more and you acquire 50% or more of the company, landholder duty applies. A buyer picking up shares in a business that happens to own its premises can face a duty bill they never modelled.
Victoria. Victoria sets its own thresholds, rates and landholder rules. A structure that is duty-efficient in Queensland can be duty-exposed in Victoria, so test the position against the state where the land and assets actually sit.
Other jurisdictions. NSW and the remaining states and territories sit outside this section, because the sources behind it do not support specific thresholds. Do not assume Queensland or Victorian numbers carry across. Confirm the position with the relevant state revenue office before signing.
Duty is a structure-sensitive cost, which is exactly why structure should not be locked in before diligence establishes what land, licences and dutiable assets are in the deal. The seller's own tax position, including the small business CGT concessions, shapes which structure they push for.
GST: going concern treatment versus input-taxed shares
Duty is structure-sensitive. GST is cash-flow sensitive, and it cuts the other way.
An asset sale is generally a taxable supply. Where the price is not stated as GST-inclusive, the buyer has to find roughly another 10% at settlement. On a $600,000 acquisition that is about $60,000, funded upfront and recovered later through a business activity statement if you are registered and entitled to the credit.
Meeting the going concern conditions
Section 38-325 of the GST Act can make the supply GST-free. The conditions are strict: the buyer must be registered or required to be registered, the parties must agree in writing that the sale is a going concern, the seller must supply everything necessary to continue the business, and the seller must carry on until the day of supply. That written agreement has to exist on or before the day of supply, which may not be your settlement date.
The practical test is whether you can carry on the same kind of business, from the same assets, immediately afterwards. Fail any condition and the whole supply becomes taxable, with penalties and interest in play. Verify the current requirements on ato.gov.au before relying on this treatment.
Why shares are different
A sale of shares is input-taxed. No GST is added to the share price, and no input tax credit is available to offset it, so a buyer who cannot recover credits may find the effective cost higher than the headline suggests.
Confirm which cash flow the price assumes before comparing structures. A fair comparison is after GST, not before.
CGT: why the seller's tax position shapes the deal you are offered
GST treatment decides the cash flow. CGT decides whether the seller will even entertain your preferred structure.
A seller's capital gains outcome diverges sharply between the two. An individual who sells shares held for more than 12 months gets the 50% CGT discount. A company selling assets gets no discount, and the gain is taxed at the company rate. That gap is why a seller whose business sits in a company often proposes a share sale first. The same transaction structured as an asset sale can be taxed very differently in their hands.
An illustrative calculation on a $600,000 sale puts the gap at $60,000 to $100,000 or more. Treat that as a demonstration of direction and magnitude, not a forecast. Your number depends on entity type, cost base, prior capital losses and ownership history.
Your CGT position is not symmetrical. In an asset sale you generally acquire assets with a fresh cost base, which sets up your own future deductions and CGT calculation. In a share sale you inherit the company's existing cost base position rather than resetting it.
Confirm the CGT events and discount rules on ato.gov.au, then have your accountant model both structures on the actual numbers.
Treat the seller's preferred structure as information. If they insist, ask what the tax difference is worth to them and whether they would rather move on price. Reading the numbers behind the business is the same discipline that makes strategic business solutions for Australian SMEs work.
Which structure suits which buyer: a decision framework
The seller's preferred structure tells you about their tax bill. It says nothing about your risk. Let diligence decide.
An asset sale suits the buyer who wants a defined starting point: a first acquisition, a business with messy or unreadable history, unresolved tax matters, unclear employee entitlement records, or a seller who will not open the books widely enough to make a share purchase safe. You buy named assets and leave the entity, its tax history and its undisclosed liabilities with the seller.
A share sale suits the buyer who needs continuity: accreditation, licences, long-term supply or customer contracts, premises where a change of control triggers a landlord right, or a workforce whose service records are part of what you are paying for. The employer does not change, so nothing needs reassigning at settlement.
The evidence should carry more weight than the listing. If the books are clean, the employment records reconcile and the tax lodgements are current, a share sale becomes far less dangerous. If they are not, price that risk into an asset structure, or walk away.
Five questions flip the decision:
Are employee entitlements fully funded?
Are there ATO disputes or lodgement gaps?
Do key contracts contain change-of-control clauses?
Does the company hold Queensland land worth $2 million or more, with 50% or more being acquired, triggering landholder duty?
Can the going-concern conditions be met at settlement?
No structure is universally better. The answer follows the parties' tax positions, your risk appetite, and what the accounts and records actually support.
Diligence checklist before you sign anything
Those questions only get answered by documents, so agree the scope in writing first: materiality threshold, lookback period, exclusions and which adviser owns which workstream.
Financial. Three years of financial statements and tax returns, plus management accounts. Debtors and creditors ageing, stock on hand, the fixed asset register. Trace related-party loans and any personal expenses run through the business, because both distort profit.
Tax. Business activity statements, PAYG and superannuation lodgement history, and all ATO correspondence. Look for disputes, payment arrangements, lodgement gaps and the franking account balance. Confirm GST registration and the basis on which the structure is expected to be treated.
Employment. Payroll records, leave balances and superannuation contributions. Award and enterprise agreement coverage, how contractors are engaged, current disputes, and any historical underpayment exposure.
Contracts and leases. Every agreement that matters, with change-of-control clauses, consent requirements, expiry dates and personal guarantees flagged. If the structure requires assignment, get the lease position early.
Legal and structural. Company and trust registers, shareholdings, charges and securities. Insurance policies and claims history, intellectual property registrations, licences and approvals, and any current or threatened proceedings.
Duty and settlement mechanics. The duty position in the relevant state, whether landholder duty could apply, and the GST treatment. Price apportionment and completion adjustments decide who pays for what at settlement.
Search limits matter too. PPSR records show security interests, not ownership, and ASIC extracts show only what has been lodged. Run them anyway; an omitted search weakens your position later.
Treat this as a structured test of the seller's statements, not a form to tick. Work through it before you commit to a structure, and the structure usually answers itself.
What verified financials show and what they do not
Financial diligence tells you what the books say. It does not tell you whether the numbers are honest. Seller-reported revenue and profit remain the market default, and that is where buyer distrust starts. Bizzie takes a different route: a seller can connect their Xero account, so a listing's revenue and profit come straight from real accounting data rather than a number typed into a form.
That solves one problem well. You can compare opportunities on figures that came out of the books, and Bizzie's free instant valuation tool gives a starting view of what a business is worth before conversations begin.
It does not solve the structure question. Verified revenue and profit say nothing about contingent liabilities, employee entitlement exposure, ATO history, or the contract terms sitting behind a change-of-control clause. A verified revenue figure confirms what was recorded in the accounting file; it does not confirm the file is complete. In a share sale, every historical exposure in the entity becomes yours, and no platform verification reaches that. The cost of getting the boundary wrong sits with you.
So split the work. Use verified financials to decide which businesses are worth investigating. Then use a lawyer and an accountant to decide whether you buy the assets or the company, and on what terms.
Your next three moves
Once verified financials have narrowed the field, the structure question moves to you. Three moves decide how it lands.
1. Get the structure in writing before you negotiate price. Ask the seller's accountant which structure they propose and why. Then have your own accountant model both on the actual numbers: transfer duty, GST and the CGT outcome, because the seller's preference usually reflects their tax position, not your risk.
2. Run diligence before you commit to a structure. The findings decide whether an asset sale or a share purchase makes sense, which warranties you need, and whether the deal is worth doing at all. Choosing the structure first and investigating second reverses the order that protects you.
3. Treat advice as a deal cost, not an overhead. A lawyer and an accountant on a share purchase cost a fraction of an unresolved ATO liability or an employee entitlement shortfall found eighteen months after settlement. Both should sign off on the structure before you sign anything.
Conclusion
The structure you choose decides what you inherit. An asset sale transfers defined assets and leaves historical liabilities with the seller; a share sale hands you the entity, its records and every exposure recorded in them. Employees, contracts, leases, transfer duty, GST and CGT all move differently depending on the path, and the seller's tax position usually explains the structure they propose.
Verified financials tell you which businesses are worth investigating. They cannot tell you what you are buying.
Your next step: before you negotiate price, have your own accountant model both structures on the actual numbers and your lawyer confirm the terms in writing. Run diligence before you commit to a structure, not after. Get that boundary right before you sign, and settlement day holds no surprises.